Restaurant insurance
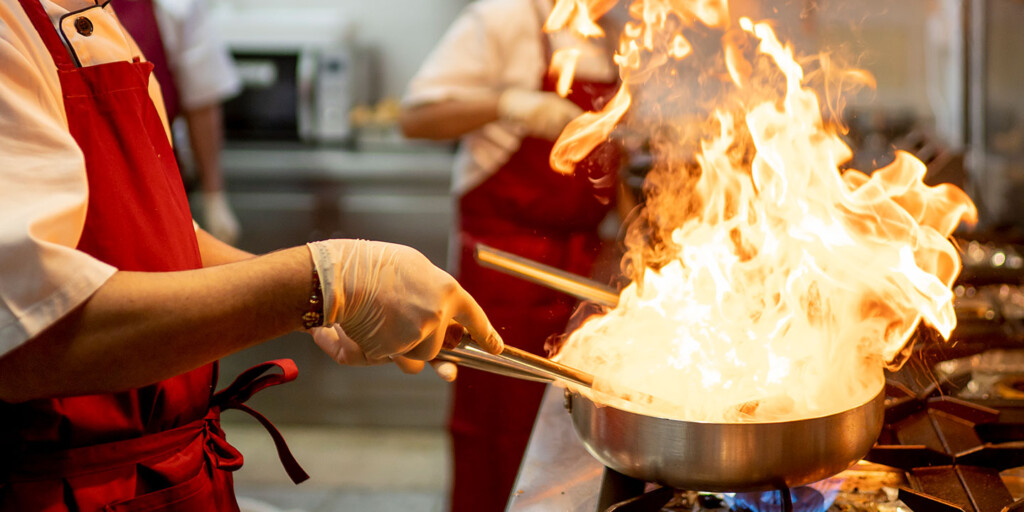
Comprehensive restaurant insurance safeguards the operational realities of dining rooms, caterers, bars, and bistros. Whether your operations involve a provincial liquor permit (RACJ), an in-house delivery team, seasonal patio seating, or corporate catering, accurately reporting your business activities ensures perfectly calibrated endorsements.
Our independent commercial brokers analyze your kitchen and front-of-house exposures to design seamless coverage without blind spots, letting you lead your brigade with total peace of mind.
Restaurant insurance is designed for caterers, bars, emerging startups, and well-established dining brands, as well as the next generation of culinary entrepreneurs across Quebec.
Types of coverage and options
Multiple coverages tailored to your situation.
-
Civil liability
No matter the services you offer, the products you sell or the location of your business, we can cover your civil liability. Civil liability protection follows you step by step and protects you in the event of accidental damage to other people or their property. This coverage is your proof of solvency! This insurance will also protect you if an accident occurs on your company’s premises or if damages are caused to the property of others.
-
Building and contents
In the event of damage caused by fire, theft, vandalism or any other risk, your building will be covered—if, of course, you are the owner of the building. This protection can also include your company buildings, their contents, leasehold improvements (if you are the tenant of the space) and your computer equipment, as the case may be. It is important to be aware of the exclusions mentioned in the contract.
-
Operating loss
Operating loss insurance covers a decrease in revenue if you have to interrupt your operations or relocate due to an incident, such as a fire. This protection can also include additional costs that may be significant during an incident. This protection allows you to keep your earnings in place until your income returns to normal. Coverage is for 12 months, but it is possible to obtain 18 or 24 months of coverage. It is important to verify the number of months needed and the time frame for replacing your equipment.
-
Food poisoning
This insurance will compensate the person who has been poisoned.
-
Commercial vehicle
Commercial vehicle insurance is determined by how you use your vehicle(s). Our protections are suitable for all types of commercial vehicles, ranging from a fleet of trucks or cars to a single vehicle used for your company or for your personal use.
-
Cybersecurity
Cybersecurity protection protects you from the consequences of theft, hacking, or data loss. This protection may cover information theft, such as payroll fraud or attempted fraud. Cybersecurity protection is now important in all lines of business.
Think about it!
Our independent brokers are insurance experts. But that’s not all!
Our team of independent insurance brokers doesn’t copy and paste coverage from one industry to another. AMR has experts for each line of business that we insure and is committed to providing coverage tailored to your activities.
Securing robust restaurant insurance requires a rigorous assessment of your operating methods. In Quebec, commercial deep fryers demand certified exhaust duct cleaning and hood maintenance (NFPA 96 standards), while liquor sales, live entertainment, and food delivery adjust your commercial general liability requirements. By disclosing these operational details to our independent brokers, you ensure policy validity and eliminate grounds for claim denials following a loss.
Managing perishable food inventory requires strict monitoring of reported property values. Within your restaurant insurance policy, commercial property coverage must encompass walk-in coolers, point-of-sale (POS) terminals, and leasehold improvements. Disclosing seasonal sales peaks allows us to attach a stock peak clause, preventing underinsurance penalties and protecting your operating margins against refrigeration failure or major structural losses.
Equipment breakdown coverage is an indispensable pillar of your restaurant insurance program. Following sudden mechanical failure or electrical arcing, it covers the repair or replacement costs for critical units—such as refrigeration compressors, walk-in coolers, commercial freezers, and convection ovens—while absorbing the financial impact of food spoilage caused by temperature changes.
Slip-and-fall injuries, severe allergic reactions, or foodborne illnesses: commercial general liability within tailored restaurant insurance shields your enterprise against third-party bodily injury claims. This essential coverage compensates affected patrons and absorbs legal defense fees, ensuring a single kitchen error or dining room accident never jeopardizes your balance sheet.
Whether operating branded company vehicles or relying on staff members’ personal cars, offering food delivery requires commercial auto coverage attached to your restaurant insurance. It absorbs on-road collision damages and third-party liabilities, bridging the critical coverage gap left by personal auto policies that strictly exclude meal delivery accidents.
Launching a new culinary venture and facing underwriting hurdles? Securing restaurant insurance for a dining startup is our specialty. Our independent commercial brokers negotiate directly with specialized insurers to build an airtight risk profile, securing comprehensive coverage before your very first meal service.
Other option
Enhance your insurance with these add-ons to your policy that offer you even more protection, for optimal coverage that can handle any situation. These protections are not always included in standard packages, so it’s best to check and make sure they are included in your contract!
-
Earthquake
With this coverage, you will be protected in the event of an earthquake that damages your commercial building and its contents. This protection is becoming increasingly valuable in the face of climate change.
-
Equipment breakdown
With this type of insurance, your company will be protected against losses caused by equipment breakdown (heating, air conditioning, refrigeration, production or transformation machinery, electronic or electrical devices). It is important to be aware of the exclusions mentioned in the contract.
-
Theft and embezzlement
Theft and embezzlement coverage provides compensation if an employee steals from you.
-
Water damage
With this coverage, you will be protected in the event of water damage to your commercial building and its contents. It is important to be aware of the exclusions mentioned in the contract.
-
Flood
With this coverage, you will be protected in the event of water flooding that damages your commercial building and its contents. It is important to be aware of the exclusions mentioned in the contract.
-
Sewer backup
The name says it all! This protection covers you against sewer backup in your commercial building. The contents will be protected and you will be compensated for decontamination, building repairs and content replacement. It is important to be aware of the exclusions listed in the policy and to have high enough amounts to cover this type of expense.
Tips and advices
-

Restaurant insurance hurdles
Why choose us?
When you choose AMR Assurances Multi-Risques, you’re opting for a team of insurance experts. More than just brokers, we are advisors who have your best interests at heart.
Our primary mission is to represent you with various insurers and to offer you a product that meets your needs. And because life moves fast, we negotiate to get you the best insurance contract at the best quality-price ratio to guarantee you peace of mind.
Don’t wait any longer!
We’re passionate about insurance
We compare the best protections
We speak your language
Water, fire, smoke or vandalism damage?
don’t panic!
We’re here to help
often occur when you least expect them. AMR Assurances Multi-Risques guides you step by step to help relieve all your worries.